What triggers the process
The moment you report an incident to your insurer, the claims process begins. That report, called the first notice of loss, sets the timeline in motion. You can usually file by phone, through a mobile app, or online. Have your policy number, the date and location of the incident, a description of what happened, and contact information for anyone else involved.
Once you file, your insurer opens a claim file and assigns an adjuster. That person is responsible for gathering facts, reviewing your coverage, and calculating what the company will pay. The adjuster works for the insurer, not for you, so it helps to document everything yourself: photos of damage, a copy of the police report if one was filed, and written notes about what happened while it is fresh.
Common misconceptions about auto insurance include the idea that filing a claim guarantees full reimbursement. What you actually receive depends on your coverage type, your deductible, and how fault is assigned.
What an adjuster actually does
The adjuster's job is to verify the facts of the loss and match them against your policy. For a vehicle damage claim, that typically means reviewing your photos, inspecting the car in person or through a third-party appraiser, and producing a repair estimate. For an injury claim, the process also involves reviewing medical records and bills.
Adjusters look at several things at once: whether the incident is a covered event under your policy, whether any exclusions apply, how much the damage is worth, and who bears fault. On fault, the adjuster will often speak with all parties and review any police report or witness statements before reaching a conclusion.
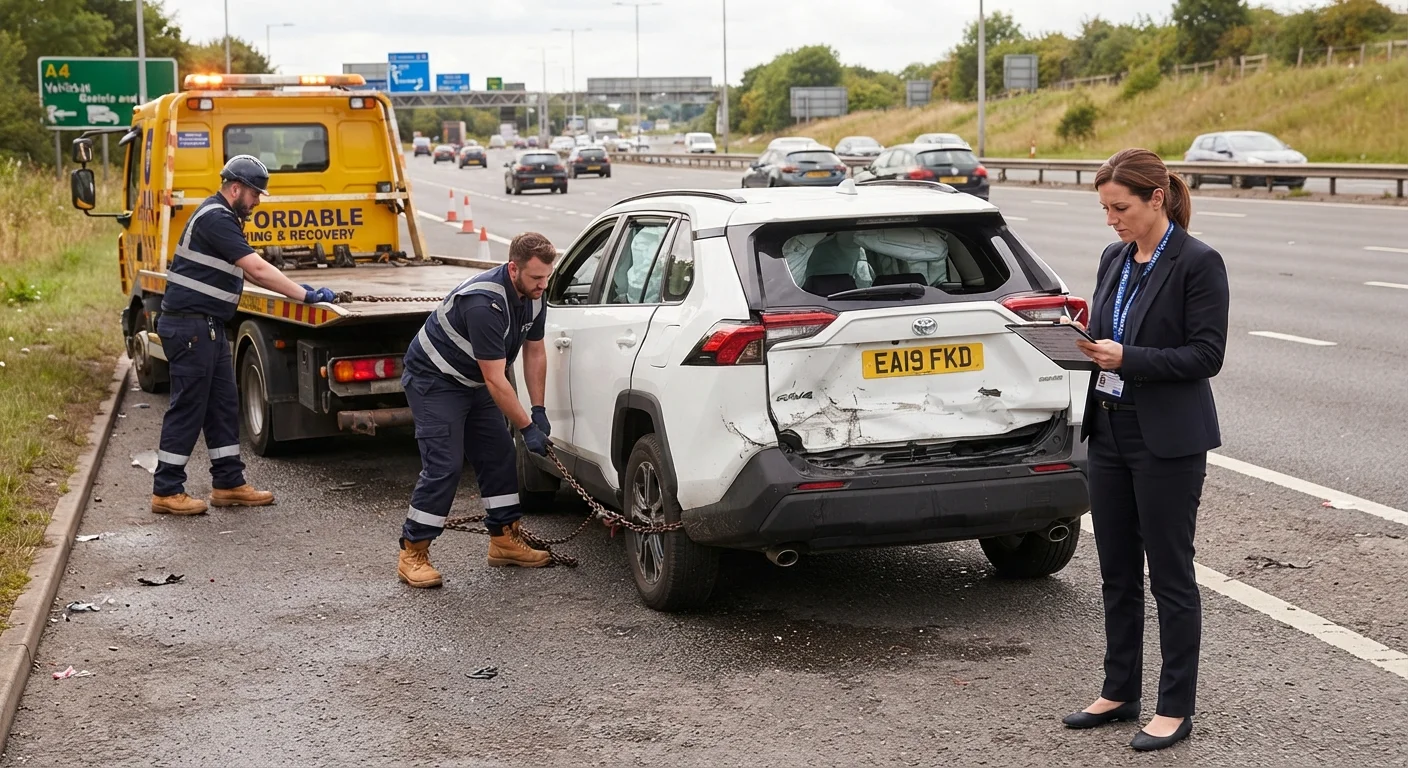
Which insurance pays after an accident depends heavily on how fault is divided and what state you are in. Some states use a no-fault system, meaning each driver's own insurer covers their injuries regardless of who caused the crash. Others assign liability based on percentage of fault, which can reduce your payout if you were partly responsible.
~6 in 10
Drivers who have filed at least one claim
According to survey data from the Insurance Research Council, most drivers will file a claim at some point in their driving life.
30 days
Common state deadline for insurer to accept or deny a claim
Many states require insurers to acknowledge a claim within a set number of days and reach a decision within 30 to 45 days, though timelines vary by state law.
$4,700+
Average collision claim payout
The Insurance Information Institute has reported average collision claim costs in this range in recent years, though actual amounts vary widely by vehicle and damage type.
From estimate to payment
Once the adjuster completes the investigation, you will receive a settlement offer. For vehicle damage, this is usually a repair estimate or, if the car is totaled, an actual cash value (ACV) figure. ACV is what your vehicle was worth just before the accident, factoring in age, mileage, and condition, not what it would cost to buy the same car new.
If your car is repairable, you can take it to a shop of your choosing in most cases. The insurer sends payment directly to the shop or to you, minus your deductible. If the car is declared a total loss, the insurer pays you the ACV minus your deductible, and takes possession of the vehicle.
You are not required to accept the first offer. If you believe the repair estimate is too low or the ACV figure does not reflect your vehicle's actual condition, you can counter with supporting documentation: independent repair estimates, comparable vehicle listings, or maintenance records that show the car was in above-average condition. Most insurers have a formal dispute or appraisal process if negotiations stall.
Before you choose or change a policy, reviewing the claims process with your insurer is worth doing upfront so there are no surprises later.
This article is for general informational purposes only and is not personalized insurance or legal advice. Coverage terms, exclusions, and claim procedures vary by insurer and by state. Always read your actual policy documents and consult a licensed insurance professional for guidance specific to your situation.