Why so many renters go without coverage
About 55% of renters in the United States do not carry renters insurance, according to data from the Insurance Information Institute. The gap is not explained by a single factor. Some renters believe the cost outweighs the benefit. Others assume their landlord's policy extends to them. Many simply have never been told otherwise.
The consequences of going uninsured are not abstract. A grease fire, a stolen bicycle, a water leak from the unit above: any of these can produce losses that run into thousands of dollars with no insurer to absorb them. Understanding which assumptions are wrong is the first step toward making an informed decision about coverage.
This article is for general informational purposes only and is not insurance, legal, or financial advice. Coverage terms, exclusions, and costs vary by insurer, policy, and state. Consult a licensed insurance agent before making any coverage decisions.
The most common myths about renters insurance
Myth
My landlord's insurance covers my stuff if something goes wrong.
Fact
A landlord's policy covers the building itself, not a tenant's personal property or liability.
This is the most widespread misunderstanding in renter insurance. A landlord carries a policy to protect the structure they own: walls, roof, plumbing, and electrical systems. If a pipe bursts and damages your furniture, your landlord's insurer has no obligation to pay you anything. The same applies after a fire or a break-in. Your clothes, electronics, furniture, and other belongings are your financial responsibility alone unless you carry your own policy. For a fuller picture of what standard property policies cover, see Home Insurance Explained.
Myth
Renters insurance is too expensive for what you get.
Fact
Renters insurance is among the more affordable personal insurance products available, with many policies costing roughly $15 to $30 per month depending on coverage limits and location.
Cost is the reason renters most often cite for going uninsured, but the math rarely supports it. A basic policy with $20,000 in personal property coverage and $100,000 in liability protection commonly runs well under $30 a month in most U.S. states. Compare that to the out-of-pocket cost of replacing a laptop, a television, and a week's worth of clothing after a theft. The premium is general information; actual quotes vary by insurer, location, and the coverage limits you choose. Always read a policy document carefully and consult a licensed agent before purchasing.
Myth
I don't own enough valuable things to make insurance worthwhile.
Fact
Most renters significantly underestimate the replacement value of their belongings when they add everything up.
Walk through any room and count: clothing, shoes, bedding, kitchen appliances, cookware, books, a phone, a laptop, a gaming console. The Insurance Information Institute has noted that the average renter owns thousands of dollars in personal property without realizing it. Replacement cost coverage (which pays what it costs to buy new items today) tends to produce higher payouts than actual cash value coverage (which deducts depreciation). Understanding the difference between those two coverage types before you choose a policy matters. Underinsured at Home covers common coverage gaps worth knowing about.
Myth
Renters insurance only covers theft and fire.
Fact
A standard renters policy typically bundles personal property coverage, liability protection, and loss-of-use coverage for temporary housing costs.
The liability portion is often the most overlooked benefit. If a visitor slips on your floor and sues you, liability coverage in your renters policy may pay for legal defense and damages up to your policy limit. Loss-of-use coverage can pay for a hotel or short-term rental if your apartment becomes uninhabitable after a covered event such as a kitchen fire. Covered perils vary by policy, so reading the specific list in any document you are considering is important. Terms, exclusions, and limits differ by insurer and state.
Myth
If I share an apartment, my roommate's policy covers me too.
Fact
Most renters policies cover only the named insured, not all residents of a unit unless they are explicitly listed.
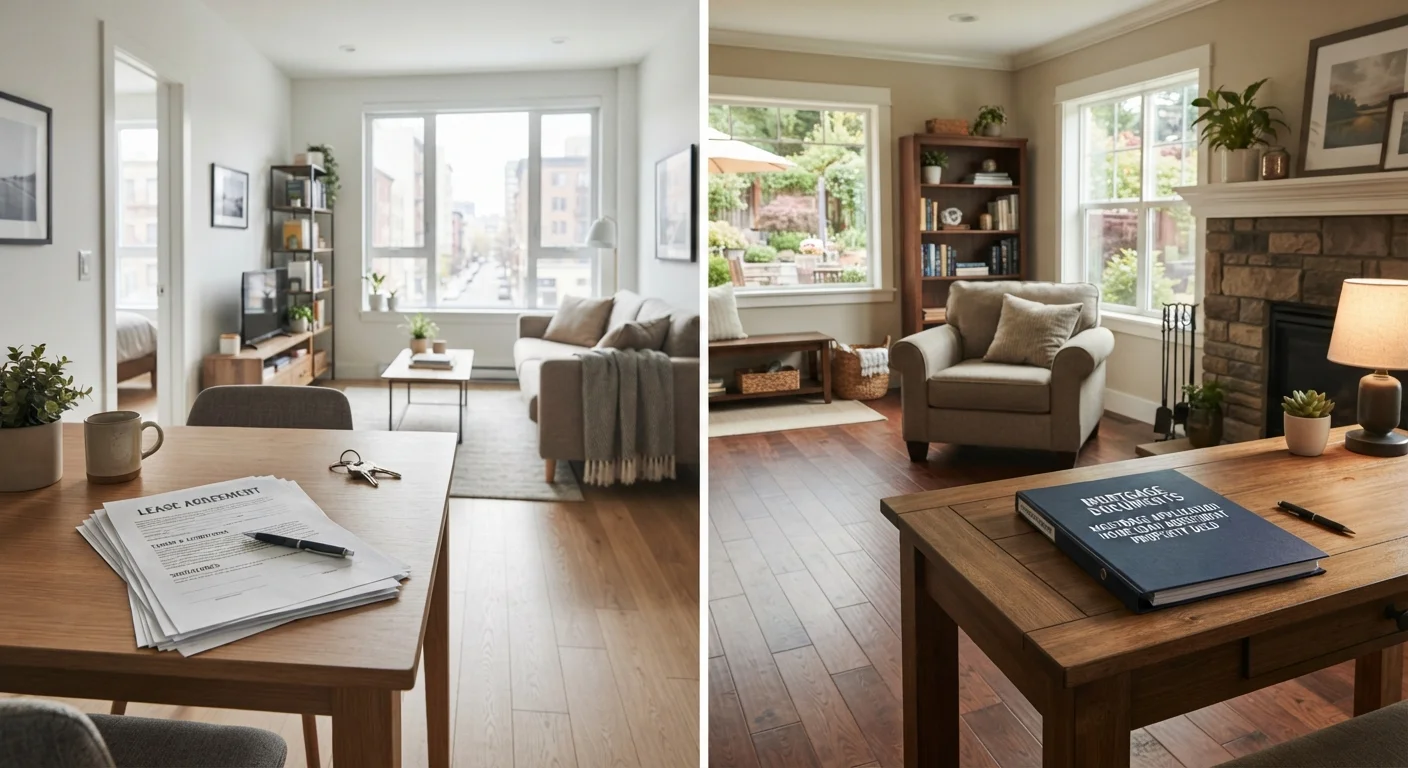
Assuming you share coverage with a roommate is a common and costly mistake. If your roommate files a claim after a burglary, your stolen property may not be covered at all unless your name appears on that policy. Some insurers allow roommates to be added, but doing so may affect both parties' claims history and premiums. Each person living in a rental generally benefits from their own separate policy. Renting vs. Owning: How Your Housing Status Shapes Your Insurance Needs walks through why housing status changes your coverage needs.
What going uninsured actually means in practice
Without renters insurance, every covered loss becomes a personal expense. That means paying out of pocket to replace belongings after a fire or theft, covering a guest's medical bills if they are injured in your home, and funding temporary housing if your unit becomes uninhabitable after a covered disaster.
Many landlords now include renters insurance requirements in lease agreements. Failing to carry a policy in that situation can put tenants in breach of their lease, with consequences ranging from a formal notice to lease termination depending on the lease terms and local law.
If you are curious how renters insurance compares to other personal insurance products, Renting vs. Owning: How Your Housing Status Shapes Your Insurance Needs is a useful reference. For parallels in other categories, Things People Get Wrong About How Auto Insurance Works shows how similar gaps in understanding affect drivers too.