How Social Security retirement benefits work
Social Security is a federal program funded by payroll taxes paid by workers and employers. When you work in a job covered by Social Security, a portion of your earnings goes toward the program each pay period. Those contributions build your eligibility over time.
To qualify for retirement benefits, you generally need 40 work credits, which most people accumulate over about 10 years of covered employment. Credits are earned based on annual earnings, and you can earn up to four per year.
Full retirement age (FRA)
The age at which you qualify for your full, unreduced Social Security retirement benefit. For people born in 1960 or later, FRA is 67.
Primary insurance amount (PIA)
The monthly benefit you would receive if you claimed exactly at your full retirement age. It is the base number the SSA uses to calculate early or delayed adjustments.
Delayed retirement credits
An increase added to your monthly benefit for each month you wait beyond your full retirement age to claim, up to age 70.
AIME
Average indexed monthly earnings. The SSA adjusts your past wages for wage inflation and averages them over your 35 highest-earning years to produce this figure, which feeds into your benefit formula.
Spousal benefit
A benefit available to a spouse (or in some cases a divorced spouse) based on the other person's work record, up to 50 percent of that person's primary insurance amount.
COLA
Cost-of-living adjustment. An annual percentage increase the SSA applies to benefits to help them keep pace with inflation, based on a measure of consumer prices.
Benefits are not automatic. You must apply when you are ready to start receiving payments. Your monthly amount is set by a formula that the Social Security Administration (SSA) applies to your lifetime earnings record, not by the total amount you paid in taxes.
If you are also thinking about health coverage in retirement, our plain-English guide to choosing health insurance covers the concepts first-time enrollees commonly find confusing.
How your benefit amount is calculated
The SSA bases your benefit on your 35 highest-earning years. Each year's wages are adjusted upward to reflect wage growth over time, producing a figure called the average indexed monthly earnings (AIME). The SSA then runs the AIME through a formula with set percentages applied at different income thresholds to arrive at your primary insurance amount (PIA).
If you worked fewer than 35 years, the SSA fills in the missing years with zeros. Those zeros bring down your average, which reduces your PIA. For this reason, people who re-enter the workforce or extend their careers sometimes see their projected benefit rise as higher-earning years replace earlier low-earning or zero years.
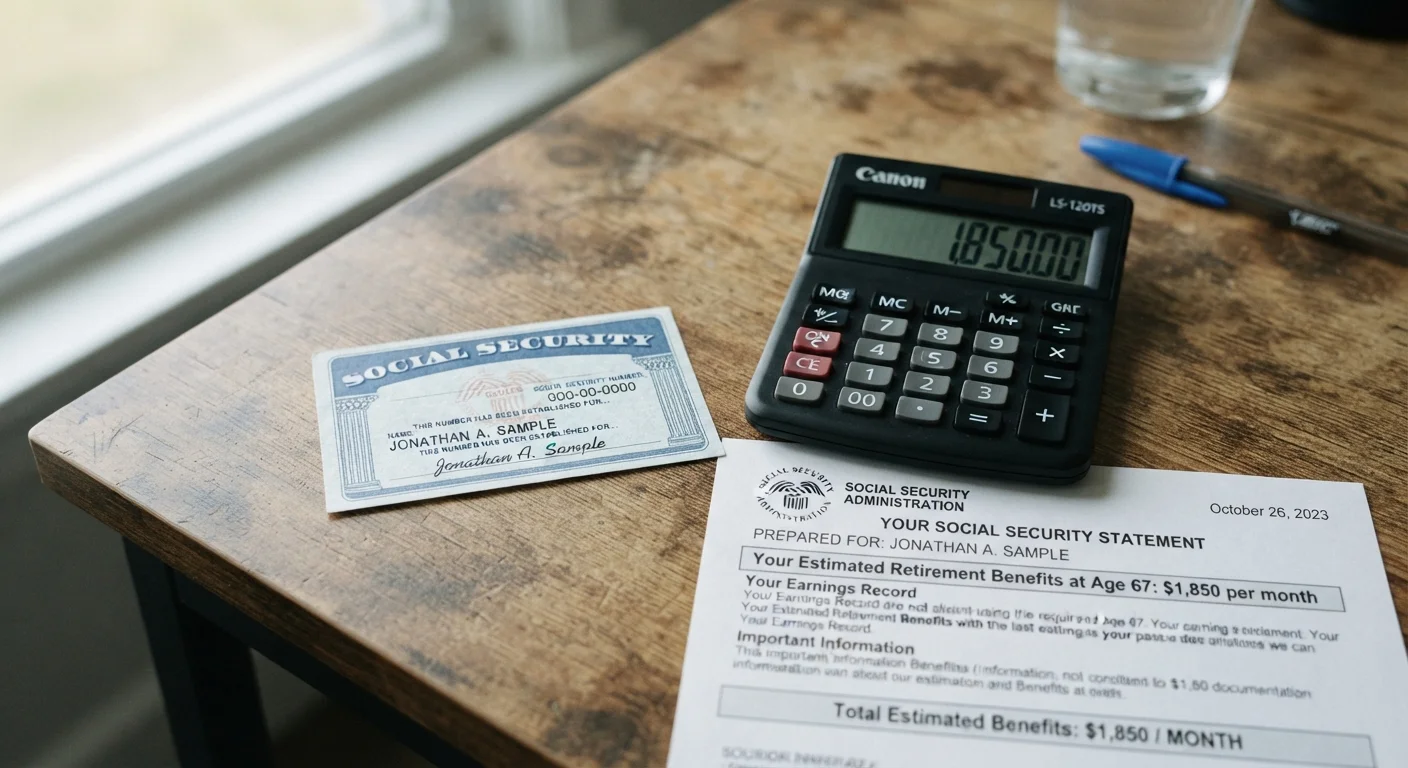
You can check your projected benefit at any age by creating a free account on ssa.gov and reviewing your Social Security statement. The statement also lists your full earnings history, which is worth reviewing for any errors. If you find a discrepancy, the SSA has a process for correcting records.
When you can claim and what timing means for your benefit
You can begin receiving benefits as early as age 62. Claiming before your full retirement age (FRA) permanently reduces your monthly amount. The reduction is roughly 5 to 6.67 percent per year for the first three years before FRA, and 6.67 percent per year beyond that, depending on how far in advance you claim.
Waiting past your FRA earns delayed retirement credits of 8 percent per year, up to age 70. There is no financial benefit to waiting beyond 70.
There is no universally correct claiming age. The decision depends on your health, other income sources, whether a spouse will claim based on your record, and how long you expect to need the income. This is general information, not personal financial advice. A licensed financial planner or Social Security counselor can help you model the options for your situation.
Check your Social Security statement annually
Your Social Security statement at ssa.gov shows projected monthly benefit amounts at ages 62, 67, and 70, along with your full earnings history. Reviewing it each year lets you catch any wage reporting errors before you claim, since correcting older records becomes harder over time.
Veterans managing both VA benefits and Medicare may also want to review how VA benefits and Medicare interact in retirement before finalizing a benefits plan.
How to enroll
The SSA offers three ways to apply: online at ssa.gov, by telephone at 1-800-772-1213, or in person at a local Social Security office. Online applications typically take about 15 to 30 minutes for straightforward cases.
The SSA recommends applying about four months before you want payments to begin. Benefits generally start the month after approval, so early submission gives time for processing. You will need your Social Security number, birth certificate, W-2 forms or self-employment tax returns from the prior year, and banking information for direct deposit.
Spouses, divorced spouses married for at least 10 years, and surviving spouses have separate eligibility rules and may be able to claim based on another person's work record. The SSA can explain which option applies in a specific situation.
What happens after you apply
The SSA sends a written decision after reviewing your application. If approved, your first payment arrives in the month following your start date, paid in arrears. Payments go by direct deposit to a bank or credit union account, or to a Direct Express debit card.
Each year the SSA announces a cost-of-living adjustment (COLA) that applies to all recipients. Your benefit increases automatically; no action is required on your part.
If your application is denied, you have the right to appeal. The appeals process has four levels: reconsideration, hearing by an administrative law judge, review by the Appeals Council, and federal court review. Most denials for retirement benefits are administrative, and many are resolved at the reconsideration stage.
Once you have benefits in place, it may also be worth exploring senior discounts and assistance programs that many older adults are eligible for but do not claim.
This article is for general informational purposes only and does not constitute financial, legal, or tax advice. Consult a licensed financial advisor or Social Security counselor for guidance specific to your circumstances.